Reviewed by Karim Eshqoor, Lawyer, Barbarian Law™ (LSO #83032R)
On an Ontario purchase, your lawyer searches title, raises requisitions, arranges title insurance, coordinates mortgage funds, prepares the statement of adjustments, registers the transfer and mortgage, and remits land transfer tax. Closing costs include LTT, title insurance, legal fees, and disbursements — ask for a written estimate early.
Somewhere between the accepted offer and moving day, someone tells you: “You’ll need a lawyer for closing.” Most buyers nod, hire one, and never quite find out what happens between then and getting the keys. Then a “statement of adjustments” arrives, closing costs appear that nobody mentioned at the open house, and the questions start.
Here’s what your lawyer is actually doing — and why the quiet weeks before closing are where your purchase is protected — for buyers and sellers across Aurora, York Region, and the GTA.
What does your lawyer do before closing?
Title search. Your lawyer searches title to confirm the seller actually owns what they’re selling, and to find everything registered against it: mortgages, liens, easements, restrictive covenants, rights of way, old charges nobody discharged. On a typical purchase, some of what turns up has to be fixed before you close.
Requisitions. Problems found on title get raised with the seller’s lawyer by a deadline set in your purchase agreement — the requisition date — requiring the seller to fix them before closing. Discharge the old mortgage, delete the expired lien, explain the easement running under your future garage.
Off-title inquiries. Title isn’t everything. Depending on the property and your title insurance, your lawyer considers taxes and utilities that could become liens, zoning and work orders, and — for condos — a status certificate review: the corporation’s finances, reserve fund, special assessments looming, and rules that might matter to you (pets, rentals, that hot tub on the terrace).
Title insurance. Nearly every Ontario purchase now closes with a title insurance policy, covering defects a search can’t reveal: fraud, errors in prior registrations, unpermitted work, survey issues. It covers your lender too. It’s a one-time premium, not a recurring cost — and it’s why some traditional searches are streamlined today.
The requisition date is a hard deadline
Title problems have to be raised with the seller’s lawyer by the requisition date in your agreement. Miss it and you may have to accept title as it is.
What happens in closing week?
This is where the choreography happens.
Mortgage instructions. Your lender sends instructions to your lawyer, who prepares and certifies the mortgage, confirms conditions are met, and receives the funds into trust. (If your deal involves a private mortgage or a VTB, this stage carries extra paperwork — and sometimes ILA.)
The statement of adjustments. The seller prepaid property taxes through December? You owe them the portion after closing. Tenant paid rent for the month? Credit to you. The statement reconciles every prepaid and accrued amount so each side pays their share to the day.
Funds in trust. Your down payment, the mortgage advance, the adjustments — everything flows through your lawyer’s trust account, and nothing moves until the moment everything is ready to move at once.
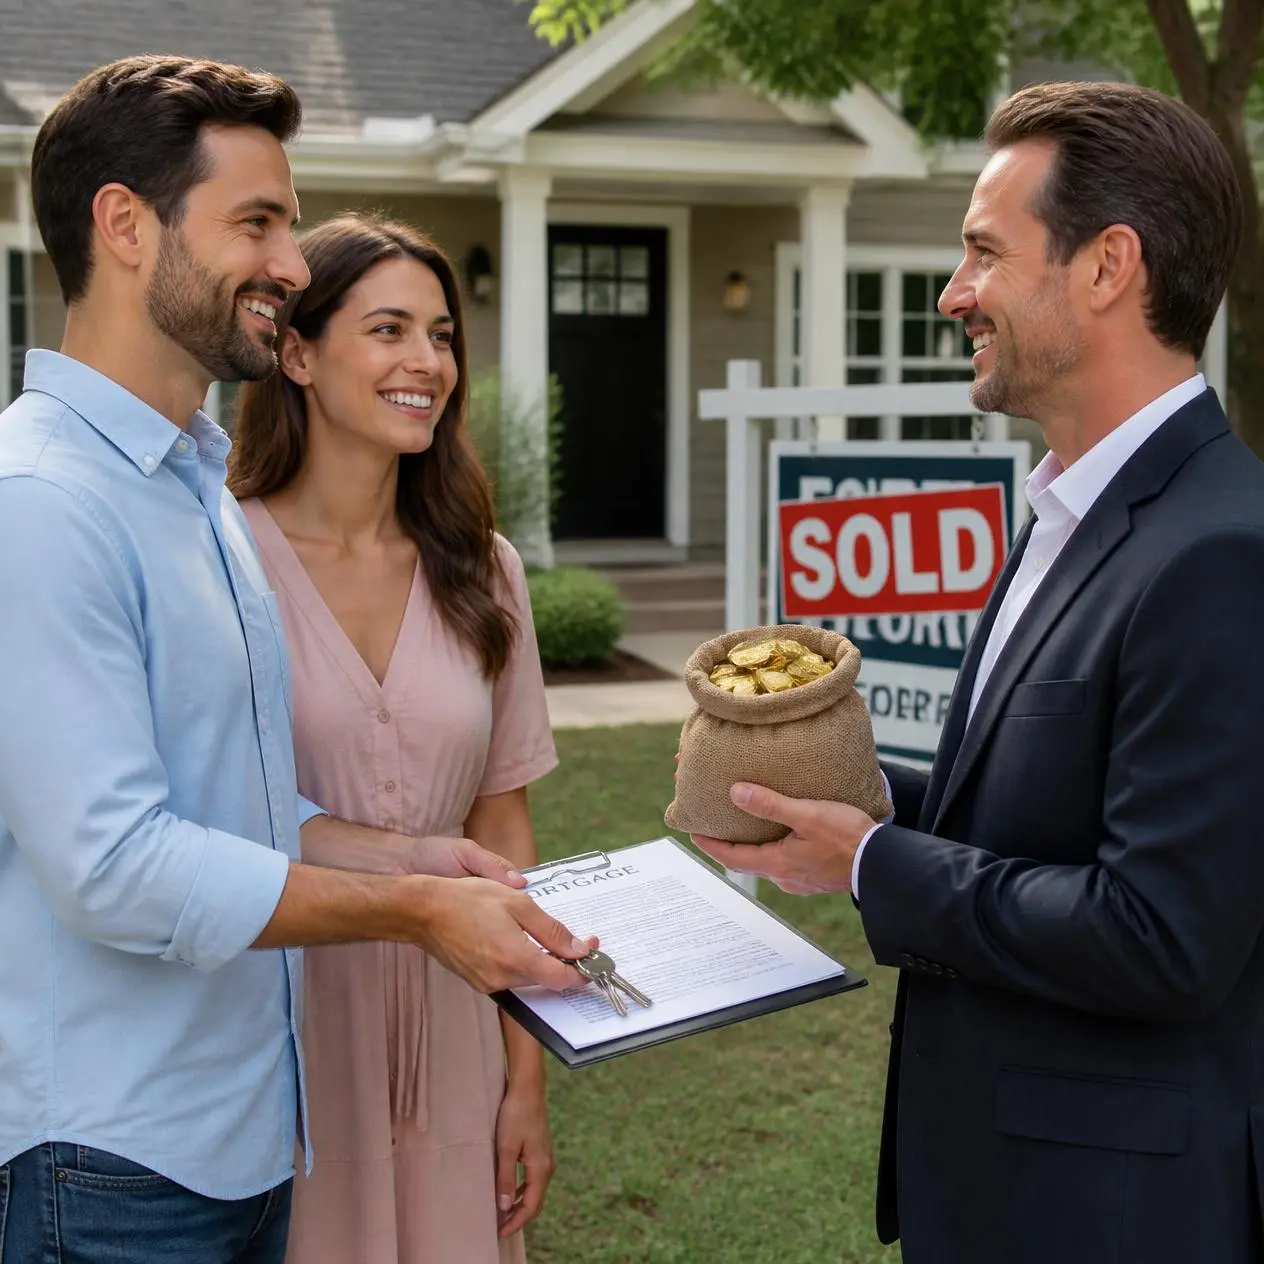
Closing day. Documents are signed and exchanged electronically between lawyers, funds are released, the transfer and mortgage are registered on title, land transfer tax is remitted — and then the only part you see: you get the keys. Afterward, your lawyer reports to you and your lender, confirming registration, title insurance, and where every dollar went.
What closing costs should you budget for?
The purchase price is not the price. Budget for:
Land transfer tax — the big one. Ontario charges LTT on a sliding scale with the price; buying in Toronto adds a second, municipal LTT on top. First-time buyers can claim a provincial refund of up to $4,000 (Toronto offers its own additional rebate), and your lawyer claims it right at registration so you never pay it in the first place — if you qualify. Eligibility is strict: never owned a home anywhere in the world, and a spouse’s ownership history can disqualify you. Your lawyer confirms eligibility under the Ministry of Finance rules before claiming it.
Title insurance premium — scales with property value; one-time.
Legal fees and disbursements — the fee covers the work above. Disbursements are third-party costs, such as searches and registration fees. At Barbarian Law™ the residential price is all-in: closing software, lender-portal charges and the LAWPRO levy are included, and only HST, land transfer tax, government registration and Teranet fees, a condo status certificate, similar-name execution letters and title insurance sit outside it. Additional discharges are $150 + HST each and other debt payouts $50 + HST each. Full breakdown: real estate lawyer fees in Ontario.
Adjustments — whatever the statement of adjustments says you owe the seller on closing day, on top of the price.
A good lawyer quotes fees up front and estimates the rest early enough that closing day holds no financial surprises. Ask for exactly that.
How much does a real estate lawyer cost at Barbarian Law™?
Real estate fees at Barbarian Law™
| Service | Price |
|---|---|
| Residential purchase, including one mortgage | $1,650 + HST |
| Residential sale, including discharge of the first mortgage | $1,500 + HST |
| Purchase and sale together | $2,950 + HST |
| Mortgage refinance | $1,250 + HST |
Residential prices are all-in except HST and the permitted disbursements: land transfer tax, government registration fees, other government fees, Teranet fees, a condominium status certificate, similar-name execution letters and title insurance.
When should you call a real estate lawyer?
Here’s the part most buyers get wrong: they hire a lawyer after signing the agreement of purchase and sale — the document that decides everything the lawyer must later live with. Conditions, the requisition date, which fixtures are included, closing date mechanics: all set before the file is even opened.
On resale homes with a standard form and a good agent, this usually works out. On private sales, assignments, rural properties, or anything unusual, get the agreement reviewed before you sign. It costs little and occasionally saves everything. See also first-time homebuyer legal mistakes.
Frequently asked questions
Does my lawyer hold my down payment?
The balance of your down payment and the mortgage advance flow through your lawyer’s trust account. The deposit you paid on signing is usually held by the seller’s brokerage until closing.
What is a statement of adjustments?
The closing statement that splits prepaid and accrued costs, such as property taxes, between buyer and seller to the day, and shows the final balance due.
Who registers the transfer?
Your lawyer, electronically, on closing day, together with your new mortgage.
The bottom line
Closing a purchase is a few hundred small verifications with your life savings on the line, ending in one synchronized exchange. You’re not paying your lawyer to fill out forms. You’re paying for the searches that catch problems while they’re still the seller’s problems, and a trust structure that means your money only moves when everything is right.
Buying or selling in Ontario? Contact Barbarian Law™ — ideally before you sign, not after. No retainer. No deposit. Invoiced after the work is delivered.
Where Art Meets Corporate Interest.
Under offer? Send us the APS before you firm up.
A lawyer who reads the agreement before it goes firm is the cheapest protection in the deal.
This article is general information about Ontario law, not legal advice, and reading it does not create a lawyer-client relationship. Every situation is different; speak with a lawyer about yours.